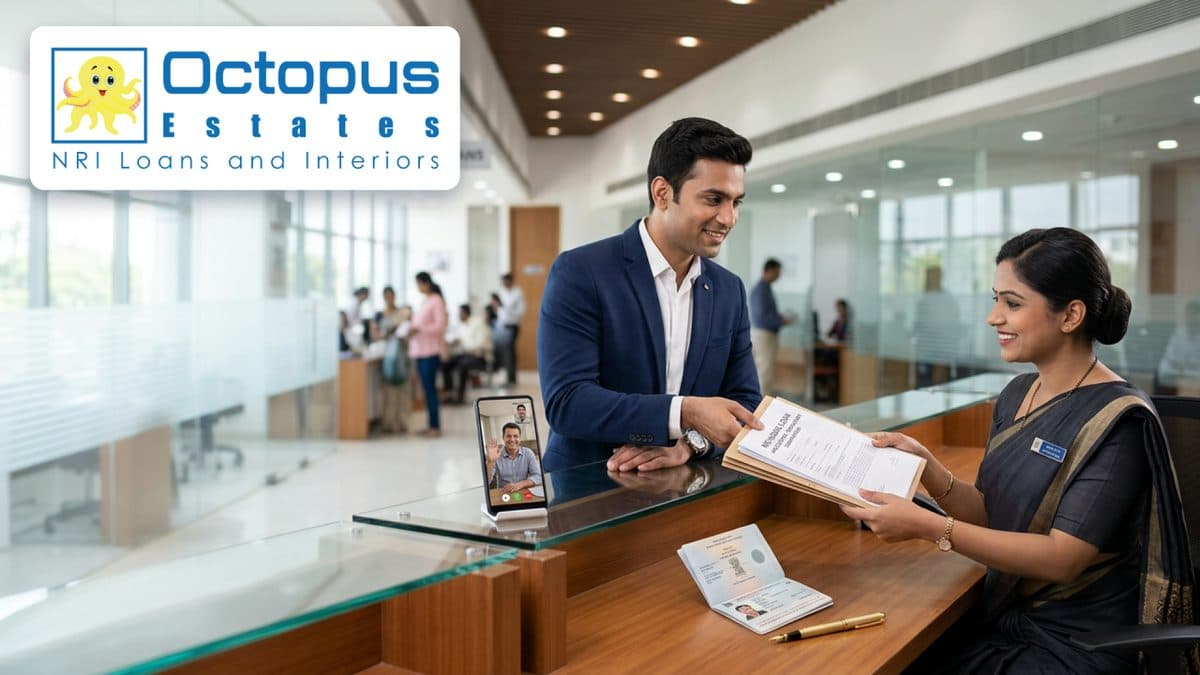
How does Octopus Estates facilitate home loans for NRI investors, navigating varying eligibility criteria and banking bureaucracy remotely?
Octopus Estates runs the full NRI home loan process remotely — matching investors to banks by eligibility, perfecting the Power of Attorney banks require, assembling overseas income documentation, and coordinating phased disbursement against construction or registration milestones.
Ameet Gogi
Leveraging home loans in India is a popular strategy for Non-Resident Indians (NRIs) looking to acquire real estate while keeping their foreign capital invested elsewhere. While Indian banks are eager to lend to NRIs, the bureaucratic process is significantly more complex than for resident Indians. Varying eligibility criteria based on country of residence, rigorous documentation demands (including overseas tax returns), and complex Power of Attorney (POA) requirements make navigating this remotely a major hurdle. Octopus Estates provides a dedicated banking and finance desk that manages the entire loan lifecycle—from pre-approval to final disbursement—ensuring smooth coordination between you, the developer/seller, and leading Indian financial institutions.
Our remote NRI home loan facilitation and advisory framework includes
- Customized Eligibility Assessment: Eligibility criteria for NRI loans fluctuate based on your resident country (e.g., GCC vs. USA/UK), employment status (salaried vs. self-employed), and income level. We conduct a preliminary assessment to match you with banks whose specific criteria fit your profile, optimizing your chances of a higher loan quantum and favorable interest rates.
- Managing the POA Requirement for Banks: Banks strictly mandate that a locally present representative must hold a registered, adjudicated Specific Power of Attorney (SPOA) to sign loan documents on the NRI's behalf. Drawing from our expertise in POA adjudication (see our guide on Specific Power of Attorney), we ensure the document is legally perfected to meet stringent banking requirements, allowing us or your nominee to execute the loan agreement seamlessly.
- Remote Documentation Management: The paper trail for an NRI loan is immense. It includes not just identity proof, but overseas salary slips, employment contracts, 6-12 months of NRE/NRO and foreign bank statements, and tax returns (P60/W2) from your country of residence. We curate, verify, and digitize your entire dossier, managing the submission to the bank to prevent processing delays due to document mismatches.
- Accessing Premier Interest Rates (Resident vs. NRI Rates): While interest rates fluctuate, our relationship managers liaison with premier institutions like SBI, HDFC, and ICICI to secure competitive floating or fixed interest rates. We ensure transparency in differentiating between standard resident rates and slightly higher NRI rates, advising you on the best financial structure for your portfolio.
- Disbursement Coordination: Securing a loan sanction letter is only half the battle. We coordinate with the bank's technical and legal verification teams for the specific property (see our guide on Occupancy Certificate checks). Furthermore, we manage the phased disbursement tranches directly to the developer (for under-construction) or the seller (for resale), ensuring funds are released strictly against construction milestones or sale deed registration.
Ameet Gogi
Octopus Estates research desk: insights on Bengaluru and Hyderabad real estate, NRI property compliance and investment planning.